Advanced Micro Devices, Inc. (AMD) continues to cement its status as a favorite among prominent Wall Street analysts, driven by surging market enthusiasm and a dominant position in the expanding artificial intelligence landscape. In the latest wave of bullish updates, Stifel Nicolaus analyst Ruben Roy has raised AMD’s stock price target from $635 to $700, representing a potential upside of approximately 10.80% from its current trading levels. Shortly after, Mizuho Securities analyst Vijay Rakesh joined the upward revision trend, lifting expectations from $580 to $705, which translates to an anticipated upside of about 11.60%.
These significant target upgrades underscore a growing consensus across major financial institutions regarding AMD’s robust growth trajectory, strategic positioning, and its capability to capture meaningful market share in some of the technology sector’s most lucrative segments. As institutional sentiment turns increasingly positive, market participants are looking closely at the underlying drivers fueling this renewed wave of confidence on Wall Street.
Why Is Wall Street So Bullish On AMD Stock?
Over the past year, AMD has emerged as one of the standout performers in the broader equities market, buoyed substantially by the historic artificial intelligence boom. The rapid commercialization and deployment of generative AI technologies have created unprecedented demand for high-performance computing hardware, presenting AMD with some of the most lucrative commercial opportunities in its corporate history.
Crucially, AMD stands out as one of the very few technology firms capable of competing directly with industry titan Nvidia (NVDA). While traditional semiconductor manufacturers like Intel also maintain a significant market presence, AMD has increasingly positioned itself as the primary challenger capable of going toe-to-toe with the market leader in high-performance graphics processing and accelerated computing solutions.
This intense head-to-head rivalry has not only validated AMD’s technological capabilities but has also made the company an exceptionally attractive asset for institutional investors on Wall Street. In the semiconductor industry, fierce competition historically accelerates innovation, leading to faster product development cycles, superior architectural designs, and ultimately, substantial financial gains. Financial analysts are clearly betting that AMD will maintain its aggressive momentum and continue riding the ongoing, multi-year AI wave to new operational and financial heights.
Anticipation Builds Around the Upcoming Q3 Financial Report
Market attention is now shifting rapidly toward AMD’s upcoming financial disclosures. The company is scheduled to release its third-quarter financial report on November 3, 2026, a date that has become a focal point for institutional investors and equity researchers alike.
A primary catalyst for the positive sentiment heading into November is the anticipated financial impact of AMD’s Helios chip series. Market watchers widely expect the upcoming third-quarter earnings report to reflect exceptionally high revenue generation driven directly by robust sales of the Helios architecture. It is highly likely that Wall Street analysts are aggressively reiterating or upgrading their positive outlooks on AMD precisely to position themselves ahead of this major earnings release.
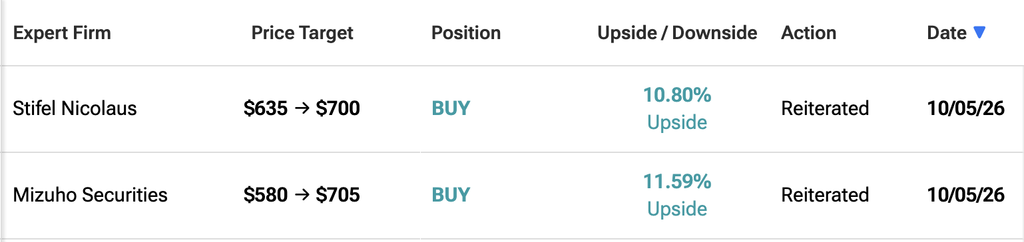
As the reporting date approaches, financial markets could see a broader wave of analysts following the strategic trajectory set by Stifel Nicolaus and Mizuho Securities, potentially leading to further upward revisions of AMD’s consensus stock price target across the financial sector. This preemptive bullishness reflects a strong underlying confidence in the company’s ability to meet or exceed consensus expectations when the official financial results are made public.
Data Centers Anchor AMD’s Long-Term Growth Thesis
Beyond individual product lines and quarterly milestones, AMD’s core data center business has firmly established itself as one of the organization’s primary cash cows. This foundational revenue stream shows no signs of slowing down over the coming years, largely insulated and propelled by the relentless global demand for advanced computing infrastructure capable of supporting large-scale AI model training and complex enterprise workloads.
Industry observers widely anticipate that the data center division will once again emerge as the top-earning business segment for AMD in its upcoming quarterly report and subsequent fiscal periods. The consistent, scale-driven expansion of the company’s data center ventures serves as a fundamental pillar supporting the bullish narrative constructed by Wall Street analysts. By continuously strengthening its enterprise offerings and securing critical partnerships within the cloud computing and corporate data ecosystems, AMD has reassured investors of its long-term viability and revenue-generating power, ensuring that the stock remains a central fixture of institutional portfolios as the technology landscape continues to evolve.