The postponement is part of a broader, accelerating trend of delayed public offerings throughout the year. While Oura faced its own specific hurdles concerning market skepticism toward single-product consumer technology brands, the broader environment for new issuances has quickly morphed into a substantial headwind. Financial analysts point to a sharp surge in bond yields as a primary catalyst dampening enthusiasm, forcing boardrooms and underwriters to rethink the timing of market debuts.
The clustering of these delays has caught the attention of market watchers who monitor the pulse of primary equity markets. According to data compiled by IPO specialist Renaissance Capital, four distinct companies spanning different economic sectors—each initially aiming to raise at least $50 million—have either announced postponements or completely pulled their initial public offerings within the span of a single week. This recent batch brings the total number of third-quarter postponements to seven, a notable escalation compared to the four companies that delayed their plans in the second quarter and the three that held off during the first.
Prior to Oura’s announcement, the pipeline had already experienced similar friction. Nuclear power component manufacturer Holtec Nuclear withdrew its initial public offering, materials firm Amaero postponed its market debut, and Bamboo Insurance pushed back its planned entry into the public sphere. These consecutive shifts suggest that broader economic variables are superseding individual corporate readiness.
Market observers note that when multiple high-profile entities step back simultaneously, it signals a systemic hesitation rather than isolated corporate missteps. The clustering of these decisions provides a clear diagnostic of current investor temperament, where macro-level anxieties outweigh internal company performance metrics.
Solid IPO Year
Despite the recent turbulence, the broader landscape for public offerings has experienced a relatively solid year overall. Renaissance Capital figures indicate that approximately $146.9 billion in proceeds has been generated across 110 separate deals, excluding activity driven by special purpose acquisition companies. These aggregate numbers have been heavily bolstered by mega-offerings that took place earlier in the year, notably massive listings from SpaceX and South Korean memory manufacturer SK Hynix during the second quarter.
Even with these massive capital raises, the broader market pace remains down compared to previous periods. Aggregate proceeds and deal counts sit roughly 30% lower than at this exact juncture in the previous year. For context, the prior calendar year witnessed 202 initial public offerings, marking the most active market environment since the historic boom year when close to 400 companies went public. Total proceeds for the current year, however, show a significant surge in overall capital volume, largely driven by the outsized contributions of the SpaceX, SK Hynix, and Cerebras offerings.
Sector performance paints a diverse picture of where investor capital is currently flowing. Healthcare and industrials are currently tied as the leading sectors for initial public offerings year-to-date, with each accounting for 24% of total market activity. The technology sector occupies the third position, representing 18% of all market launches so far.
Performance in the aftermarket has been mixed. Approximately 59% of all offerings launched are currently trading at or above their initial public offering price. However, some of the year’s largest and most visible offerings, including SpaceX, SK Hynix, and Cerebras, have notably lagged behind their initial pricing marks, creating a cautious atmosphere for subsequent large-scale debuts.
Macroeconomic Headwinds
In recent months, a combination of macroeconomic factors and mounting concerns regarding the massive capital expenditures tied to the artificial intelligence buildout have begun to weigh heavily on the primary issuance market. The anticipated autumn pickup in market activity fell short of projections as broader economic pressures set in.
Analysts at Renaissance Capital highlighted these pressures in a report distributed to clients, pointing to a confluence of factors that stalled momentum. Concerns regarding the efficiency and return on investment for AI infrastructure spending, combined with bond yields hitting 19-year highs and the resumption of interest rate hikes by central banks, have combined to create a formidable barrier for companies looking toward an autumn market debut.
The benchmark Renaissance IPO ETF reflected this trajectory, peaking in June earlier in the year around the time of the high-profile SpaceX market launch before encountering subsequent downward pressure. Industry experts suggest that while enthusiasm for foundational technology remains robust in certain pockets, the broader financial architecture supporting new market entrants has tightened significantly.
The enthusiasm for artificial intelligence infrastructure remains palpable in private circles, particularly for physical assets like data centers, but investors are increasingly viewing these components through a pragmatic lens. The underlying mechanics of the infrastructure buildout are frequently categorized by market participants as increasingly commoditized, prompting a more selective approach to valuation.
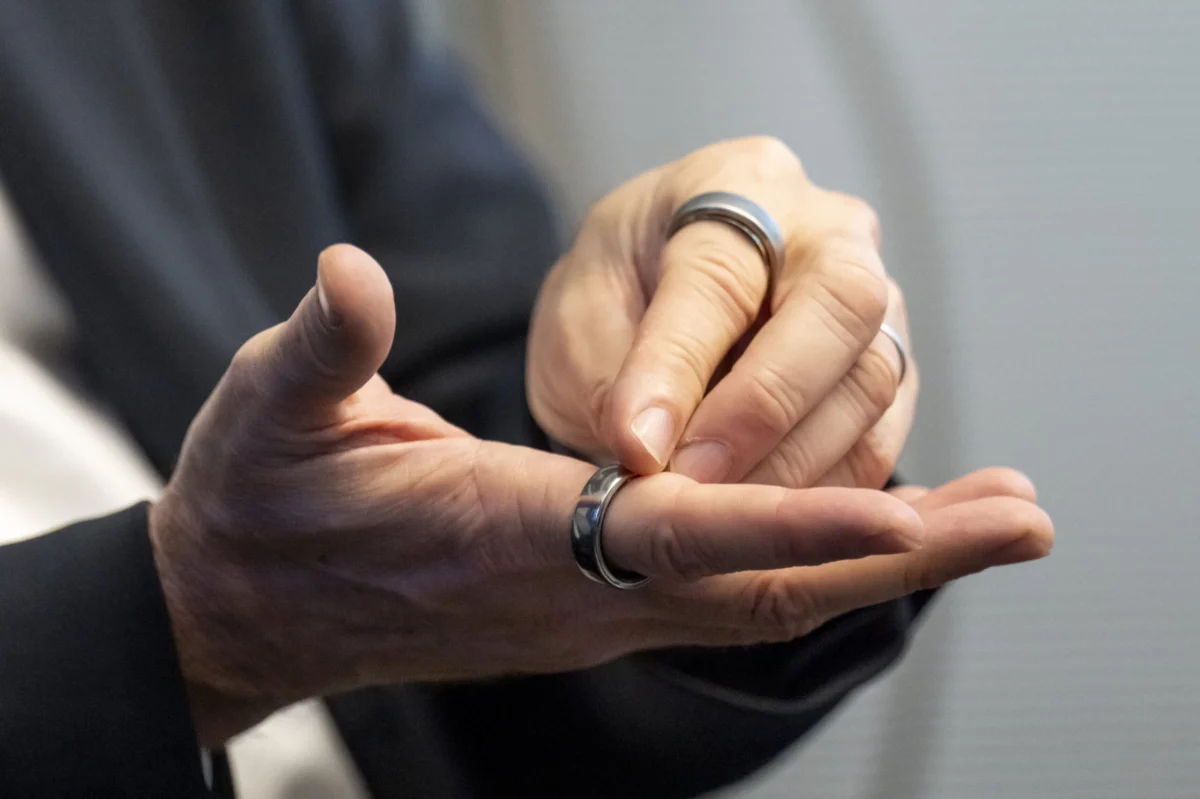
Beyond macroeconomic pressures, analysts suggest that Oura faced unique scrutiny due to the nature of its core business model. Unlike diversified technology conglomerates or software-as-a-service providers with broad product suites, Oura’s commercial success is heavily concentrated in a single physical product category: the biometric smart ring.
This narrow focus has drawn comparisons to previous consumer hardware trends that left public market investors nursing heavy losses. Market historians point to previous waves involving wearable and fitness technology brands where rapid initial growth eventually collided with saturation and intense hardware competition.
For public market investors who remember past downturns in single-product consumer technology hardware, caution has become the default reaction. The hesitation surrounding Oura’s valuation and reception is widely viewed as a reflection of skepticism toward narrow consumer hardware ecosystems rather than a broader indictment of the technology sector at large.
Compounding these market dynamics is the evolving ecosystem of private capital. Companies seeking substantial funding no longer face a binary choice between remaining small or enduring the rigorous, highly scrutinized process of a public listing. The growth and maturation of private credit and alternative funding sources have provided modern enterprises with viable, highly flexible alternatives.
The depth, complexity, and availability of private capital have expanded exponentially in recent years. For many high-growth companies, tapping into private markets allows them to secure substantial capital without the immediate compliance burdens, public transparency, and short-term earnings pressures associated with operating a publicly traded company. When market conditions in the public sphere fail to deliver the desired valuation, private alternatives offer a reliable safety valve, allowing businesses to patiently wait for more favorable macroeconomic windows.