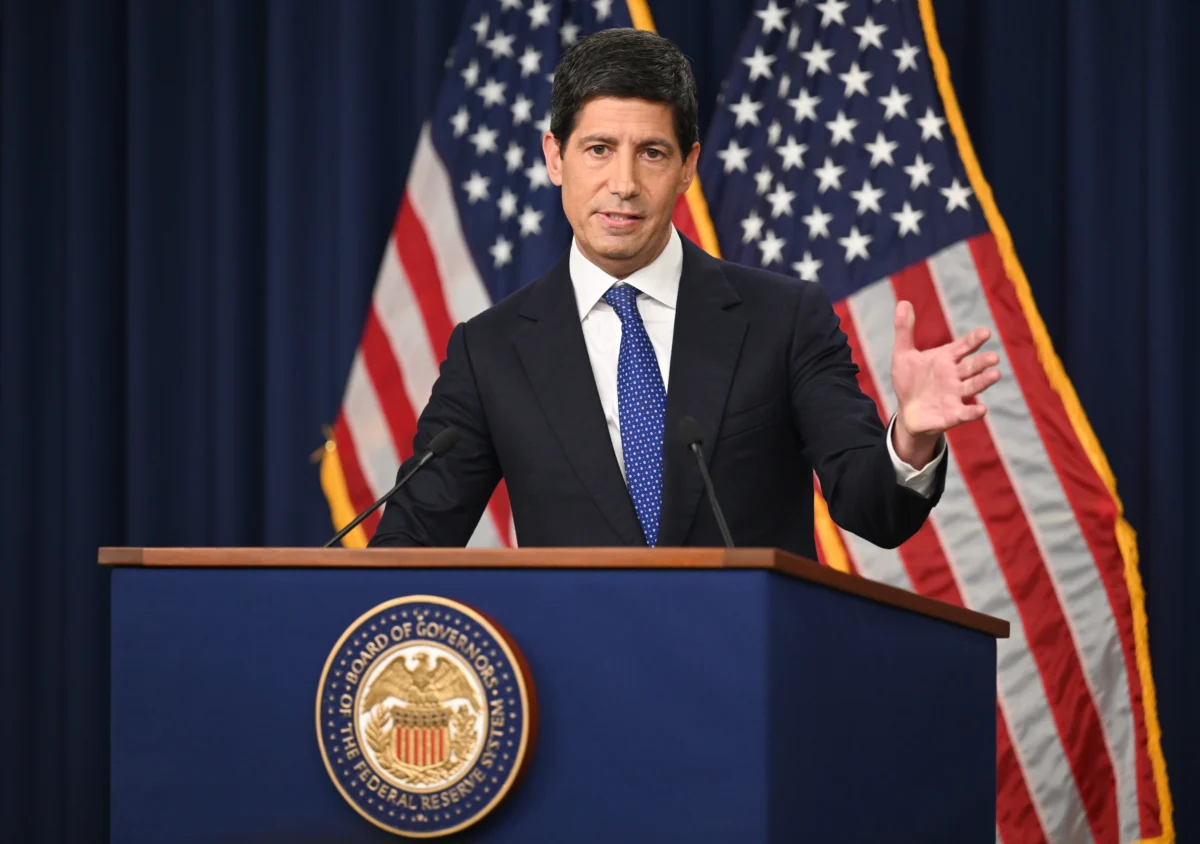
WASHINGTON — With a few carefully chosen words during a high-stakes press conference at Federal Reserve headquarters, Chairman Kevin Warsh both explained this week’s momentous decision to hike interest rates and raised vexing questions about the future path of monetary policy.
Warsh described Wednesday’s decision to lift the central bank’s benchmark interest rate by a quarter percentage point not specifically as a tightening of economic policy, but rather as removing "a dose of accommodation." Further, he emphasized that the move was made possible because of a U.S. economy that appears to have noticeably "strengthened" alongside financial conditions that have become progressively less restrictive.
While the language may initially sound like standard central bank semantics, it strikes directly at the heart of a fierce debate currently playing out across global financial markets: Just how far will the Warsh-led Fed go if it has only removed a single "dose" of help, and what foundational guidelines or metrics will policymakers actually use to formulate policy moving forward?
That specific phrase immediately registered on Wall Street as the one stand-out hawkish element of Warsh’s post-meeting commentary, according to Krishna Guha, head of economics and central bank strategy at Evercore ISI, in a detailed client note.
"This was not a mistake; it was a phrase he repeated several times and looked very much a deliberate choice to frame policy in this way," Guha added, noting that the overall framing is substantively different from the communication style utilized by the Fed in recent years. Furthermore, it raises the distinct possibility of a much more open-ended approach regarding the total number of rate hikes that might ultimately be required to tame the economy.
Historically, the Federal Reserve’s policy framework has heavily included a strict calibration of where the federal funds rate should sit relative to the so-called neutral rate—a theoretical equilibrium level that neither actively boosts nor holds back economic growth. By historical extension, benchmark rates that sit well above this neutral rate are considered restrictive, while those hovering closer to or below neutral are regarded as accommodative stimulus.

What About Neutral?
Warsh’s specific framing of the latest rate hike as merely removing "a dose" of accommodation could easily be interpreted as the first of multiple deliberate steps toward withdrawing monetary support that the central bank no longer feels is necessary for the broader economy. The overarching mandate for the Fed remains returning inflation sustainably back down to its target of 2%, and policymakers generally consider raising borrowing costs as an effective way to tamp down runaway demand and control persistent price pressures.
"Warsh’s framing, if taken literally, raises the possibility that rates might have to keep going up until financial conditions facing the private sector are no longer ‘accommodative’ — however that is defined," Guha said in his note. "This is a relatively open-ended prospect."
During the press conference, Warsh was given a clear opportunity to clarify precisely what benchmark or metric he was using to determine just how much accommodation remains embedded in current policy.
Asked by CNBC’s Steve Liesman to explain how far he sees the current rate — which now sits in a target range of 3.75% to 4% — resting above neutral, Warsh essentially rejected the traditional framing altogether. In doing so, he delivered a statement that runs counter to how central bank policy has operated for more than a decade.
Warsh stated candidly that measuring the benchmark rate relative to a theoretical neutral rate is "useful academically. It’s a discussion to help us think about policy. Do I think it has any operational effect of decisions that we make today? No, I don’t."
That striking answer helped add an immediate layer of mystery to a Fed chairman who is rapidly developing a reputation for being notably cryptic when it comes to expressing how he views the underlying machinery of monetary policy and how it needs to be tuned.
Markets Wonder What’s Next
That ambiguity immediately triggered a furious round of post-meeting speculation across Wall Street regarding what the central bank plans to do next.

One of the most immediate reactions from major financial institutions was the swift pricing-in of higher odds for another interest rate hike when the Federal Open Market Committee next gathers in October. Goldman Sachs quickly added an October rate increase to its official macroeconomic forecast, joining Bank of America, which similarly expects another move before the year concludes in December. The market-implied odds of an October increase hovered near 58% on Friday morning, according to data from CME Group’s widely watched FedWatch gauge. Just a week prior, that same probability stood at roughly 42%.
"The word ‘accommodation’ means ‘stimulus’ at the Fed; this comment implies that the current monetary policy stance is meaningfully stimulative," wrote James Egelhof, chief U.S. economist at BNP Paribas Securities, in a note to clients.
"With policy starting at a stimulative stance, a strong cyclical impulse, and persistent inflation, we think significant rate increases, perhaps more than the three we expect, may be necessary to stabilize the unemployment rate from below and prevent overheating next year," Egelhof added, echoing the sentiment that the "dose of accommodation" remark was easily the most striking feature of Warsh’s abbreviated news conference.
Financial markets are increasingly pricing in the distinct likelihood that the Warsh Fed will remove a few more "doses" of accommodation before it considers its work finished. Current futures pricing implies a federal funds rate of approximately 4.635% near the end of 2027, an outlook that strongly argues for three or four more rate hikes still ahead.
If that scenario ultimately materializes, the Fed will, at the very least, completely undo many of the FOMC rate cuts that were previously approved under Warsh’s predecessor, Jerome Powell, who now serves as a regular member of the committee as a governor.
The remarks regarding a "dose of accommodation" seemingly helped to underscore this newly established hawkish tone, implying that the policy committee no longer views the overall stance of monetary policy as even modestly restrictive, according to Jack Janasiewicz, portfolio manager and lead portfolio strategist at Natixis Investment Managers Solutions.
"We remain unconvinced that this is the start of an aggressive new tightening cycle," Janasiewicz noted, offering a more measured perspective on the unfolding situation. "Rather, we see this as a removal of the insurance cuts the Fed delivered in the fall of 2025."