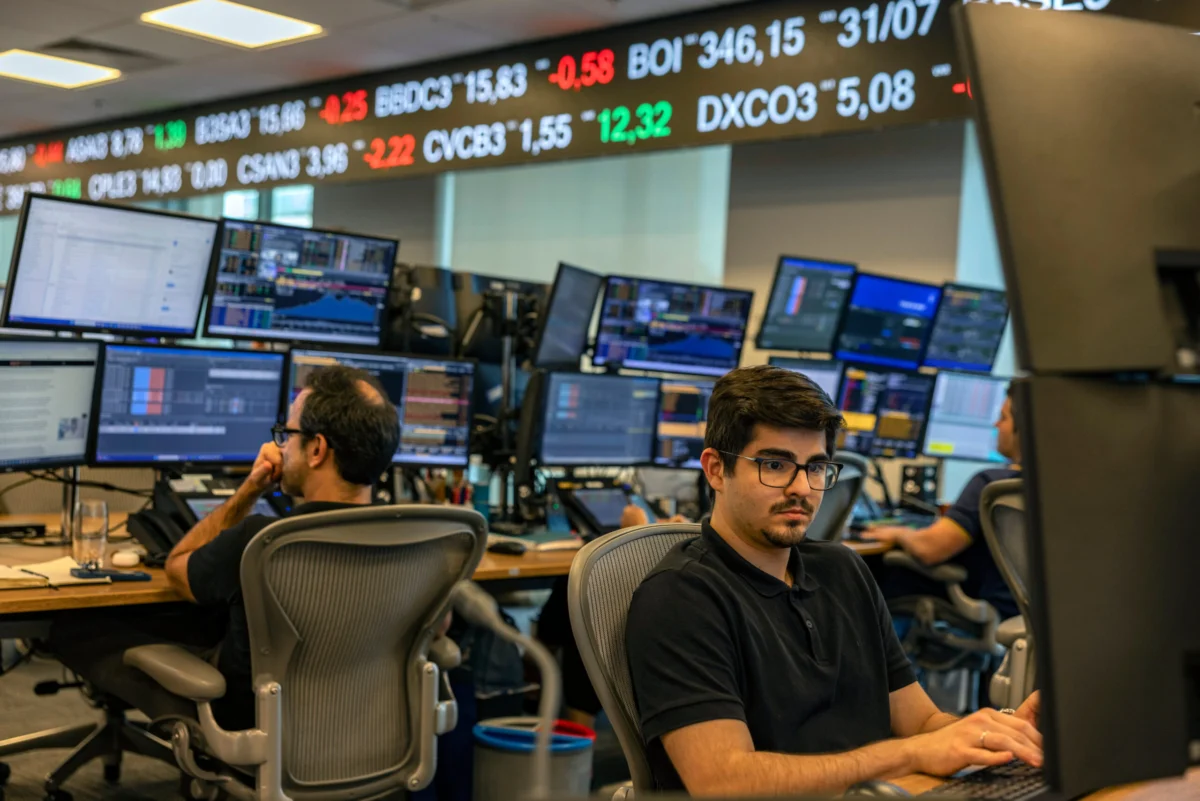
SAO PAULO — Latin American equities are making a formidable statement on the global financial stage, significantly outperforming major developed market benchmarks as a confluence of macroeconomic tailwinds, robust commodity markets, and a shifting political landscape breathe new life into the region’s capital markets.
As measured by the iShares Latin America 40 ETF (ILF), the region is handily beating the S&P 500 year-to-date, posting a gain of 15% compared to the S&P 500’s 11% advance. More broadly, the asset class has surged by more than 70% since late 2024, prompting institutional investors and wealth managers around the globe to re-evaluate their allocations toward emerging markets in the Western Hemisphere.
Yet, as the market reaches these notable milestones, a central question remains on the minds of portfolio managers and institutional strategists: Can this momentum continue?
In a comprehensive new report, Ernesto Revilla, Chief Latin America Economist at Citi, answers that question with a qualified affirmative, noting that sustained outperformance hinges critically on whether regional economies can effectively seize the moment.
"Latin America is poised for take-off. Or to be more precise: the conditions for Latin America to achieve a higher rate of growth are the best they have been in decades, and it is time to capitalize on the opportunity," Revilla wrote in the research note.
According to Citi’s analysis, the structural tailwinds currently supporting the region represent some of the most favorable conditions seen in decades. Among the most prominent drivers are a weaker U.S. dollar, elevated commodity prices, favorable geopolitical realignments, and a wave of recent elections that have brought pro-business and pro-reform leaders to power across multiple key jurisdictions.
Revilla emphasized that a weaker U.S. dollar serves as the primary catalyst for the region’s broader financial success. When the greenback softens, global investors actively seek out markets with stronger currencies and higher prospective returns. Furthermore, sovereign and corporate debt repayment becomes notably cheaper for emerging market entities that traditionally borrow in U.S. dollars, while internationally traded commodity prices tend to appreciate.
This favorable external environment is further bolstered by increasingly mature and sophisticated central banking institutions across Latin America. Modern monetary authorities in the region have demonstrated an exceptional capacity to control inflation—a notable departure from historical precedents characterized by severe inflationary shocks.
Consequently, real interest rates in Latin America rank among the highest globally, generating attractive carry trade levels reaching as high as 10% in Brazil, according to the Citi report. These lucrative yields have served as a powerful magnet for fixed income and foreign exchange inflows. At the same time, these elevated rates leave ample room for future monetary easing cycles, which market participants anticipate will provide an additional catalyst for regional equities.
Best countries to capitalize
Beyond these overarching macroeconomic advantages, the report underscores compelling, country-specific catalysts driving investor optimism. In Mexico, for instance, the economy stands to benefit directly from the artificial intelligence boom through the export of advanced computing hardware, such as central processing units assembled within its manufacturing hubs. Meanwhile, Argentina is undergoing what economists describe as the most market-friendly political and economic shift in a generation.
Danny Osorio, CEO of Andean Capital Advisors, observed that private capital flows into Latin America have experienced a notable re-energization as the region establishes a degree of economic stability not seen in years. Osorio, whose firm advises asset managers, family offices, and sovereign wealth funds, noted that he is actively witnessing a substantial repatriation of capital back into countries such as Colombia, Peru, Ecuador, and Argentina.
This renewed financial interest is also being reinforced by a deliberate strengthening of diplomatic and economic ties between the United States and Latin America. Earlier this month, U.S. Secretary of State Marco Rubio undertook high-profile diplomatic visits to Colombia, Ecuador, and Peru—nations closely aligned with the current U.S. administration. The diplomatic outreach underscores the White House’s strategic focus on the Western Hemisphere, a priority explicitly articulated in both the National Security Strategy and the National Defense Strategy, which have called for a modern renewal of the Monroe Doctrine, colloquially referenced by analysts as the "Donroe Doctrine."
This geopolitical pivot coincides with a broader electoral cycle across the region that has seen voters elect leaders who favor stable currencies, expanded international trade, more open market economies, and deeper integration with the United States.
The risks
Despite the prevailing optimism, financial analysts and regional experts caution that Latin America is not entirely immune to external shocks and structural risks. The single greatest potential threat to the ongoing rally remains the prospect of a sustained rise in U.S. interest rates.
"If the U.S. sneezes interest rate wise, that’s full-on pneumonia for Latin America," warned Osorio, highlighting the region’s historical sensitivity to tightening monetary policy by the U.S. Federal Reserve.
In addition to monetary policy risks, both Revilla and Osorio pointed to climate-related vulnerabilities, specifically the disruptive weather patterns associated with El Niño. The cyclical phenomenon has triggered severe droughts and flash floods across various parts of the continent, directly threatening the vital agricultural export sectors in nations such as Colombia and Peru.
Equity analysts at Citi also acknowledge that regional markets have enjoyed an exceptionally strong run, noting that a significant portion of the near-term opportunity has already been priced into current asset valuations. For the equity rally to sustain its momentum, corporate earnings growth will need to accelerate. Such fundamental improvements, analysts argue, could encourage global investors to expand their underweight allocations to the region.
"Even a modest reallocation of global capital toward the region could have a meaningful impact," wrote Andres Cardona, Director of LatAm Equity Research for Citi.
Signs of such capital reallocation are already emerging. Institutional investors in Europe have funneled more capital into Latin American equities so far in 2026 than they have in the past 16 years combined, according to data from Morningstar cited by The Financial Times.
How to play it
Market participants looking to deploy capital in the region are increasingly focusing on sectors benefiting from structural penetration and demographic tailwinds. Osorio noted that Latin America remains largely underbanked, presenting substantial long-term growth opportunities as the expansion of modern financial services gathers pace. Access to consumer credit, including mortgages and automotive loans, is becoming more widely available to the region’s growing middle class than ever before.
Among individual corporate success stories, Nu, the digital bank founded in Brazil that has since successfully expanded its operations into Colombia and Mexico, continues to capture strong institutional backing. Morgan Stanley currently maintains an overweight rating on the financial technology firm with a price target of $21, up from its recent trading level just under $14. The company further burnished its growth profile this month by announcing plans for an official expansion into the United States market.
Meanwhile, Brazil faces a critical near-term domestic catalyst—and potential source of market volatility—as the nation’s high-stakes presidential election approaches in a matter of weeks.
Recent public opinion polling has revealed that Flavio Bolsonaro, the more business-friendly right-wing candidate, is running neck-and-neck with current President Luiz Inácio Lula da Silva. The poll, which marks the first major survey showing Bolsonaro within striking distance of the presidency, triggered a sharp, positive market rally on the Bovespa exchange. The first round of voting is scheduled for October 4, with a subsequent runoff election slated for October 25.