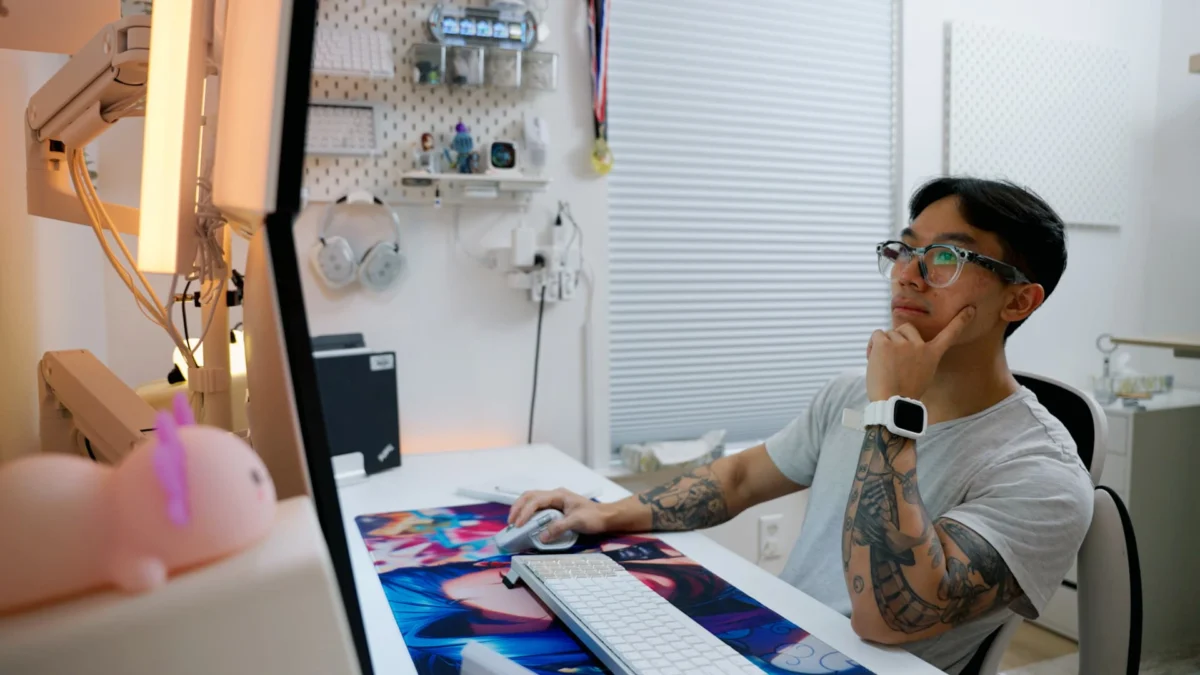
HOUSTON — During a late night at home in May 2021, Hy Luu, a 29-year-old engineering consultant, sat at his computer researching how to obtain more capital to invest in shares of Tesla. It was then that he discovered margin investing: the practice of borrowing money from a broker to purchase securities like stocks, using existing investments as collateral. The mechanism promised greater buying power, allowing investors to pay back the loan as the underlying stock appreciated in value. The principal risk involved a margin call—an urgent demand to deposit additional cash or securities into the account if the value of the portfolio fell below a specific threshold.
At the time, the arrangement struck Luu as an efficient path forward. Living with his mother, Kim Nguyen, in a three-bedroom, two-bathroom house in Houston, Luu decided to consult her. Given that she had previously worked as an accountant and happened to still be awake that evening, her perspective carried weight. The 66-year-old retiree found the financial concept interesting, and that modest reassurance proved to be the catalyst he needed.
It was not long before Luu began utilizing margin to acquire Tesla shares. Roughly a year later, he had amassed more than $100,000 in margin debt.
"I went really crazy," Luu told CNBC in an interview. "The stock was going up, and so I was like, ‘There’s no way I could lose.’"
After five years of navigating margin investing—including a turbulent period in 2022 when he worried that further declines in Tesla stock would trigger a mandatory margin call—Luu has been working to manage his largest margin balance to date. In June, he exercised $165,000 on five Tesla call options, acquiring 500 shares at $330 per piece. Factoring in the available cash in his account, the transaction pushed his total borrowing past $156,000, coinciding with a month where Tesla shares swung widely from below $370 to over $430.
By combining his Tesla investments with his company stock and 401(k), and subtracting his accumulated margin debt, car loan, and student loans, Luu’s net worth has climbed from negative territory seven years ago to more than $800,000.
"I’m very close to becoming a millionaire," the investor said, while quickly acknowledging the inherent danger of his approach. "What I’m doing is risky. I don’t recommend anyone do it."
Luu’s strategy places him squarely within a broader, rapidly expanding trend taking hold across the contemporary financial markets.
‘Gambling with an asterisk’
Retail investors are increasingly turning to borrowed money to amplify their market exposure. Data from major retail brokerages underscores the shift. Robinhood’s margin book climbed to a record $21.6 billion in the second quarter, representing a 127% increase year over year and a 332% surge from the $5 billion recorded in the second quarter of 2024. To qualify for margin trading on the platform, eligible users are required to maintain a minimum portfolio value of $2,000.
"Robinhood has made a really concerted effort to go after customers that are actively using margin because they’re the most active traders," said Devin Ryan, head of financial technology research at Citizens.
Brokerage firms often stand to benefit from margin activity by collecting interest on loans, while highly active clients generate valuable trading-related revenue. According to Ryan, competitive offerings over recent years—including transfer bonuses, low margin rates, and high yields on cash balances—have successfully targeted this demographic. At the same time, other segments of brokerages are expanding; Robinhood’s retirement assets, for instance, have nearly quadrupled over the past two years.
Analysts point out that technological accessibility has played a significant role in fueling the trend. The frictionless nature of smartphone applications allows users to execute complex financial transactions instantly.
"Having very little friction in investing and having everything at your fingertips, and then having a really seamless mobile experience where it’s not clunky, I think, plays a big part of that," Ryan said.
A Robinhood spokesperson told CNBC that its product ecosystem is designed to appeal to a diverse customer base. "We don’t believe it’s accurate to characterize" transfer promotions as specifically targeting active margin traders, the company stated, adding that it aims to "meet users where they are" and "reject any implication" that the platform encourages risky trading behaviors.
The expansion of margin debt extends far beyond a single brokerage. Total margin debt across the broader financial system reached an all-time high of approximately $1.5 trillion in June, according to statistics compiled by the Financial Industry Regulatory Authority (FINRA). This figure encompasses borrowing by institutional participants, such as hedge funds, alongside retail accounts.
While not every dollar of rising margin debt stems from new risk-taking—some increases occur automatically as rising equity prices adjust the valuation of existing positions—market observers argue that the trend reflects a broader psychological shift. Sam Huszczo, chief investment officer at SGH Wealth Management, suggests that the ongoing market bull run, marked by multiple record highs, has amplified speculative behavior.
"That’s greed," Huszczo said, noting that while the sentiment may not be pervasive across every asset class, it is "certainly creeping into pockets."
"Margin, that’s only the tip of the iceberg of what we can see," he continued. "Fear of missing out is just the emotion of jealousy with a brokerage account."
Huszczo maintains that the underlying market remains healthier than many assume, though he cautions that escalating margin debt and the proliferation of high-risk instruments like leveraged exchange-traded funds introduce systemic fragility. He stresses the importance of distinguishing between legitimate momentum growth investments and reckless chasing, while reiterating the standard advisory guidance that portfolios should avoid over-concentration in a single stock or sector.
Despite such warnings, Luu’s focus has remained anchored on Tesla since he purchased his first share in late 2019. Having started his current job earlier that year with virtually no knowledge of investing, he was introduced to the stock market after a coworker recommended downloading a trading app.
"I started making money, and I quickly learned, ‘Now I’m making money, what do I do with it?’" Luu recalled. "I started investing in index funds and even in crypto, and then I did the math. I looked at the returns, and I was like, ‘This is very slow returns. I’m never gonna reach retirement, financial independence until like 65.’"

His conviction was solidified that same summer when he test-drove a Tesla Model 3. Initially intending only to experience the vehicle without any purchase in mind, Luu placed a reservation the very day of the drive and took delivery two weeks later. Convinced that electric and autonomous vehicles represent the future, he views Tesla as his most straightforward investment, holding his shares steadfastly over a seven-year span.
The conviction was severely tested in 2022, when Tesla suffered its worst year on record, plunging roughly 65% to close at $123.18. The steep decline placed Luu in immediate danger of a margin call. Seeking capital to protect his position, and with his mother’s approval, he made a consequential financial move.
"I refinanced the house to get access to an extra $30,000 of capital, and I used that to pay down my margin debt," he said.
Reflecting on his prolonged reliance on borrowed funds, Luu describes his approach as "gambling with an asterisk." Although Tesla shares have risen over 43% over the past five years to trade around $375—down roughly 25% from its all-time high near $499—he believes his strategy relies on psychological discipline rather than blind luck.
"It’s very easy to see it as gambling, because obviously all your money is in one stock, and that’s inherently risky," he said. "But the reason why I say there’s nuance to it is because it’s a matter of investing temperament, financial discipline and time horizon."
Maintained across decades with high conviction, his approach insulates him from panic selling during market downturns, he argues. Yet, financial strategists note that liquidity crunches during market corrections can severely limit an investor’s ability to capitalize on discounted equity prices.
Affecting equities
Historically, elevated levels of margin debt have frequently preceded risk-off periods across the broader equity markets.
Data from Fundstrat Global Advisors indicates that whenever monthly margin debt has expanded by more than 45% year over year since 1960, the stock market subsequently declined in five out of six instances. June’s record reading registered at 49% year-over-year growth, even as the S&P 500 continued to post double-digit gains for the year. A reversal into negative territory by year-end would mark a rare deviation from historical precedent.
Furthermore, Fundstrat’s analysis shows that median performance for the S&P 500 tends to deteriorate over a 12-month horizon following a 40% breakout in margin debt growth compared to a one-month window. The median 12-month forward return following such spikes is a decline of 4.2%, contrasted with a median one-month drop of 2.2%. In essence, rapid expansions in leverage tend to foreshadow heightened medium-term volatility.
While leverage itself does not initiate market downturns, economic strategist Hardika Singh notes that significant debt accumulation severely magnifies downward momentum when corrections begin.
"The premise of gains beget gains, it turns into losses beget losses, and that’s what’s troublesome," Singh said. "You have these losses, they keep piling up, and then the stock gets sold, and everyone’s starting to close out their position, and it becomes this huge train wreck that’s very hard to stop, and it adds a lot of volatility to the market."
At the same time, Singh acknowledges the rationale driving retail participants toward aggressive positioning. "No one ever got rich by diversifying," she observed.
A new hobby
For Luu, who describes himself as a lifelong hobbyist with varied interests ranging from rock climbing to playing the guitar, investing has evolved into another pastime, complete with a social media channel documenting his financial journey. Should he reach his ultimate financial milestones, Luu maintains he will continue participating in the markets, potentially expanding into entities like SpaceX.
This perception of trading as a leisure activity reflects a broader cultural shift. Singh points out that many younger American investors feel compelled to assume outsized risks to achieve financial security. She links the phenomenon to "financial nihilism," a mindset where individuals navigating challenging labor markets and persistent inflation gravitate toward volatile financial tools.
"It makes a lot of sense why individuals, specifically retail investors, keep gravitating towards this margin debt," Singh said. "This is like a drug, and I think people just can’t get enough of it in this economy."
Conversely, experienced market participants warn that the dangers of leveraged trading far outweigh potential windfalls. Kevin Davis, a 59-year-old retail investor who spent years working in the music industry before transitioning to a career as a stockbroker and technology platform owner, cautions against borrowing against securities.
"It’s gambling. You’re borrowing money you don’t have, and so if it goes the other way, now you have a clock on your money, and it’s ticking," Davis said. "The market’s not going to save you. It never does. Don’t play the margin game."
Despite the warnings, Luu retains the steadfast support of his family.
Luu pursued engineering largely because his father, who passed away from lung cancer in 2012, introduced him to computing at an early age. According to his mother, Luu shares both the physical features and the determined character of his late father.
Asked to reflect on what her husband might have thought of their son’s high-risk financial strategy, Kim Nguyen paused briefly with a gentle smile.
"He would’ve said he’s proud of him," she said.